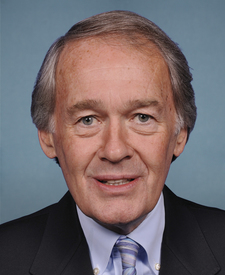
Edward J. Markey
Senator Ed Markey (D-MA) presents a clean self-dealing profile across public records. His financial disclosures show holdings concentrated in diversified mutual funds and index funds (Fidelity, TIAA-CREF) rather than individual stocks, so there is no STOCK Act individual-trading activity to score. His reported net worth has grown to roughly $1.9M-$3.8M, but this growth is consistent with market appreciation of broad-market funds rather than salary-independent enrichment. Standard correlation concerns exist around telecom/tech industry money given his long Commerce Committee tenure, but he is widely regarded as a net-neutrality and pro-regulation champion who has frequently opposed those industries' positions. No campaign personal-use violations, family-lobbying ties, or fundraising-versus-work scandals surfaced; his lifetime missed-vote rate (~2.9%) is near the Senate median, with one notable 80% miss spike during the 2020 COVID period that coincided with his re-election primary.
Public record
- In Congress since
- 1975
- Committees
- Small Business and Entrepreneurship (Ranking Member)
Commerce, Science, and Transportation
Environment and Public Works
Health, Education, Labor, and Pensions - Missed votes, 119th Congress
- 0.8% (7 of 915; median member 1.9%)
- Campaign money, 2025–26 cycle
- $5.4M raised · 11% from PACs & committees · $1.3M cash on hand FEC ↗
The stock-trading ban
H.R. 7008 bans new stock purchases by members, spouses and dependents; it doesn't force sales of existing holdings. The Senate vote was on the version paired with the SAVE Act, which is why no Democrat voted yes. Full breakdown →
Disclosed stock trades
No periodic transaction reports on file since 2024. That's the norm: most members don't trade individual stocks, or hold them in blind trusts and diversified funds.
Amounts are the ranges members must report, not exact values. The STOCK Act requires a report within 45 days of a trade; "late" counts days past that deadline, measured to the filing date.
How the score breaks down
Sources behind this score: 2 data aggregator · 4 reference database · 2 official record · 1 news reporting. Score = weighted average of the components that have data; the 2 without sourced evidence are excluded, never counted against the member. Methodology →
Embed this score on your site
Updates automatically when the score changes.
Right of reply
Is something here wrong or missing context? Members and their staff can send a correction or a statement. Statements are published on this page in full, and corrections go in the public log. Email corrections@greederboard.com.